Traumatic Brain Injury Claims in Texas: Proving the Full Cost of a Life-Altering Injury

A serious head injury rarely announces itself the way a broken bone does. A person may leave a crash on I-45 or a fall at a job site talking and walking, then spend the following months struggling with memory, concentration, mood, and the ability to work. For families, the hardest part is often realizing that the injury is not a single event with a single bill. It can reshape the household for years.
In short, a Texas brain injury claim is generally evaluated by looking at medical expenses, future care needs, lost income and earning capacity, and the effect on the person’s quality of life, and the long-term projections are usually where insurers push back hardest. Anyone who has had a head injury should be evaluated by a medical professional, and worsening confusion, repeated vomiting, seizures, or loss of consciousness call for emergency care.
I spent over a decade as an insurance adjuster before becoming an attorney, handling complex, high-value claims that included catastrophic injuries. I later practiced insurance defense and now represent injured people through Herrera PLLC. That background taught me how insurers evaluate brain injury claims, and why the long-term picture is where those claims are most often contested. This article explains, in general terms, how brain injury claims are approached in Texas and what goes into documenting their full cost.
Why Insurers Undervalue the Long-Term Cost of a Brain Injury
In my experience, brain injuries are among the injury types where insurers work hardest to minimize long-term damage projections. The reason is simple arithmetic. A brain injury can mean permanent disability, lifetime medical needs, and lost earning capacity. When those projections are stretched over decades, the numbers are large, and a carrier that can shrink them reduces its exposure.
From my years on the carrier side, I know how that shrinking tends to happen, in general terms:
- Emphasizing early recovery. Emergency records may show a patient who was alert and stable, and an insurer may point to that as evidence the injury was minor.
- Treating symptoms as temporary. Cognitive and emotional changes may be described as short-term, even when treating providers expect them to continue.
- Questioning the connection. Insurers may suggest that symptoms stem from something other than the accident.
- Narrowing the future. Estimates of future care may assume fewer services, for fewer years, than the injured person’s providers anticipate.
None of this is unusual, and none of it means an insurer is acting improperly in every case. But it explains why the projection of future costs, not the emergency room bill, is often the center of a serious brain injury claim.
Mild, Moderate, and Severe TBI: How Classification Affects Your Claim
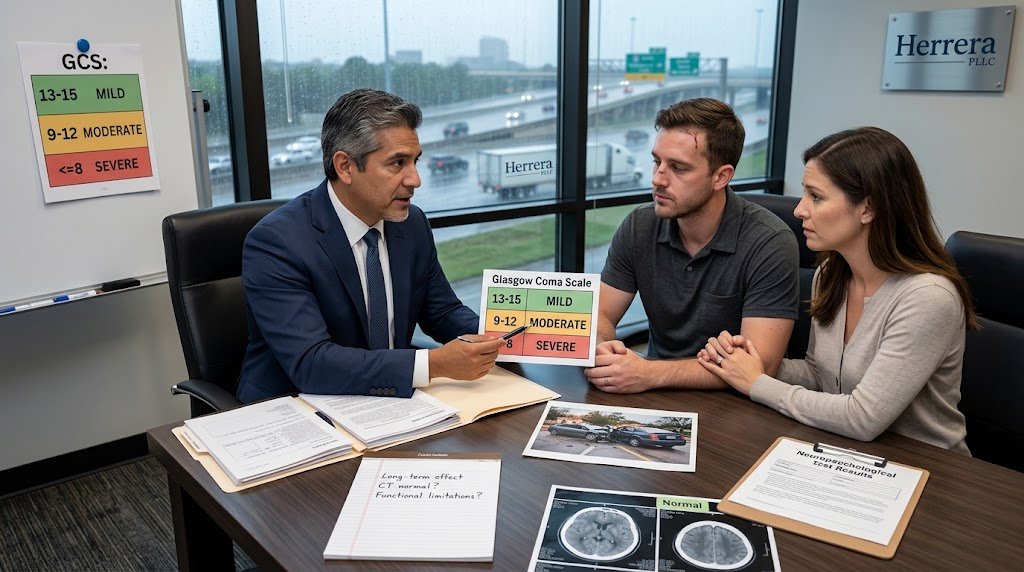
Medical professionals commonly describe traumatic brain injury as mild, moderate, or severe, often using the Glasgow Coma Scale, which scores a person’s eye, verbal, and motor responses. By the scale’s common cutoffs, scores of 13 to 15 are classified as mild, 9 to 12 as moderate, and 8 or below as severe, and mild injuries are often called concussions. The Centers for Disease Control and Prevention publishes information on the potential effects of TBI and TBI facts and statistics that readers may want to review directly. Public health sources also acknowledge that classification systems have limits.
Classification matters in a claim because it influences how an injury is perceived. The word “mild” in a medical chart can describe the initial severity of the event, and it does not necessarily describe the lasting effect on a person’s life. An insurer may seize on the label and treat a “mild” diagnosis as proof that serious long-term consequences are unlikely. A person with a so-called mild injury may still have symptoms that disrupt work and family life, and the opposite can be true as well: a severe injury may require care that is difficult to price in advance.
Mild injuries can also be harder to document. Imaging such as a CT scan may appear normal, and cognitive effects are often documented through neuropsychological testing and the observations of treating providers. For that reason, the label alone rarely tells the whole story. What tends to matter more is what treating providers document over time: symptoms, functional limitations, treatment, and prognosis. Our brain injury attorney page describes how Herrera PLLC approaches these cases.
Brain injuries also occur in many kinds of accidents. They are associated with car accidents, pedestrian accidents, and commercial vehicle crashes on Houston-area highways such as I-10, I-45, and Highway 288, including truck rollover accidents and underride and override accidents. Our overview of truck accident cases explains how those claims differ from standard auto cases. Brain injuries also come from falls and from construction and industrial accidents, which are common in a city with Houston’s building activity and industrial facilities.
Building a Life Care Plan With Medical and Vocational Experts
A life care plan is a document that projects the future medical and support needs of a person with a long-term injury, along with their estimated costs. In brain injury cases, the firm’s approach emphasizes properly evaluating future medical costs and life care planning, because those projections are what insurers most often try to reduce.
A life care plan is generally built with input from professionals rather than from a lawyer’s estimate. Depending on the injury, that input can include:
- Treating physicians and specialists, who can address diagnosis, treatment, and prognosis.
- Rehabilitation and therapy providers, who can describe the services a person has needed and may continue to need.
- Vocational experts, who can speak to how an injury affects the ability to work.
- Other qualified experts, where the facts call for them.
I use experts where necessary, and I treat the plan as something that has to be supported by the medical record. A projection that cannot be traced to a provider’s findings is easy for an insurer to dismiss.
Texas law also shapes how past medical costs are proved. Section 41.0105 of the Civil Practice and Remedies Code limits recovery of medical expenses to the amount actually paid or incurred by or on behalf of the claimant, so the bills that count are not always the full amounts a provider first charged. Health insurers and hospitals may also assert reimbursement claims or liens against a recovery, which can affect what a family ultimately keeps.
Texas also publishes public information on brain injury services. The Texas Health and Human Services Commission has pages on acquired brain injury and Comprehensive Rehabilitation Services, along with a handbook chapter on TBI and spinal cord injury post-acute rehabilitation services. The Texas Brain Injury Advisory Council is also part of the state’s structure. These pages can help families understand what services exist. They are not a substitute for a medical or legal evaluation, and eligibility for any program depends on its own rules.
Spinal cord injuries raise similar long-term questions, and some accidents cause both. Our page on spinal cord injury cases covers that area.
Lost Earning Capacity After a Cognitive Injury
When someone cannot return to work, or can only work in a reduced capacity, the loss goes beyond the paychecks already missed. Texas law allows a person to seek compensation for lost income, and in some cases for the loss of future earning ability, meaning the difference between what a person was likely to earn and what they can now earn.
Texas also has a specific proof rule. Under Section 18.091 of the Civil Practice and Remedies Code, evidence of lost earnings or lost earning capacity must be presented as a net loss after reduction for income tax, and the court instructs the jury on whether the recovery is subject to income tax. In practice, that means economic and vocational experts often present earnings losses on an after-tax basis.
Cognitive injuries make this harder to measure. A person may still be physically able to do a job but struggle with the memory, attention, or processing speed it requires. Limitations of this kind are often less visible to an employer or an insurer, and may be easy to downplay.
Documentation tends to matter here: medical records describing functional limits, employment history, and, where appropriate, vocational analysis that connects the injury to what the person can now do. A family trying to understand the financial picture generally benefits from looking at the whole career horizon, not just the next few months.
Non-Economic Damages for Personality and Relationship Changes
Many families say the hardest losses are the ones no invoice captures. A parent who becomes irritable or withdrawn. A spouse who no longer remembers recent conversations. A teenager whose personality seems to have changed.
Texas law recognizes non-economic damages. Chapter 41 of the Civil Practice and Remedies Code defines them to include losses such as physical pain and suffering, mental or emotional pain or anguish, loss of consortium, physical impairment, disfigurement, loss of companionship and society, and loss of enjoyment of life. Insurers often treat these losses with skepticism because they are subjective and harder to quantify. Showing them usually depends on testimony from the people who know the injured person best, and from providers who have treated them.
The Legislature publishes Chapter 41, the damages chapter of Texas law, on its website, along with related provisions in Chapter 18, Chapter 41, and Section 41.0105. Readers can review them directly. How they apply to a particular claim is a question for an attorney. Texas does not generally cap non-economic damages in an ordinary negligence case, although caps apply in certain contexts, and Chapter 41 limits exemplary (punitive) damages by formula. Where an injury was caused by a drunk driver, Texas law may allow punitive damages in addition to compensatory damages if the legal standard is met, and the cap on punitive damages does not apply to certain intoxication-related offenses.
Why These Cases Take Longer to Settle Fairly
Brain injury cases are often not ready to be resolved quickly, and that is not a defect in the process. A person’s condition may take time to stabilize. Providers may need time to understand what recovery is realistic. Settling before that picture is clear risks resolving the claim for less than the long-term need.
Insurers sometimes use that timing. Early offers can arrive while a family is under financial pressure and before the long-term effects are known. A settlement generally ends the claim, so it matters to have the full picture before one is accepted.
The amount of available insurance also shapes these cases. In catastrophic injury claims, the at-fault party’s policy limits, and any uninsured or underinsured motorist coverage the injured person carries, can determine how much can realistically be recovered, so identifying all potential sources of coverage is part of evaluating a claim.
Time limits are the counterweight. Texas generally sets a two-year statute of limitations from the date of injury for most personal injury cases. In wrongful death cases, the period is two years from the date of death. Claims against government entities, including cities, counties, and state agencies, require written notice within six months. Limitations can be tolled in some circumstances, such as when the injured person is a minor, and other notice requirements can apply, so the deadlines in any particular case should be confirmed with an attorney.
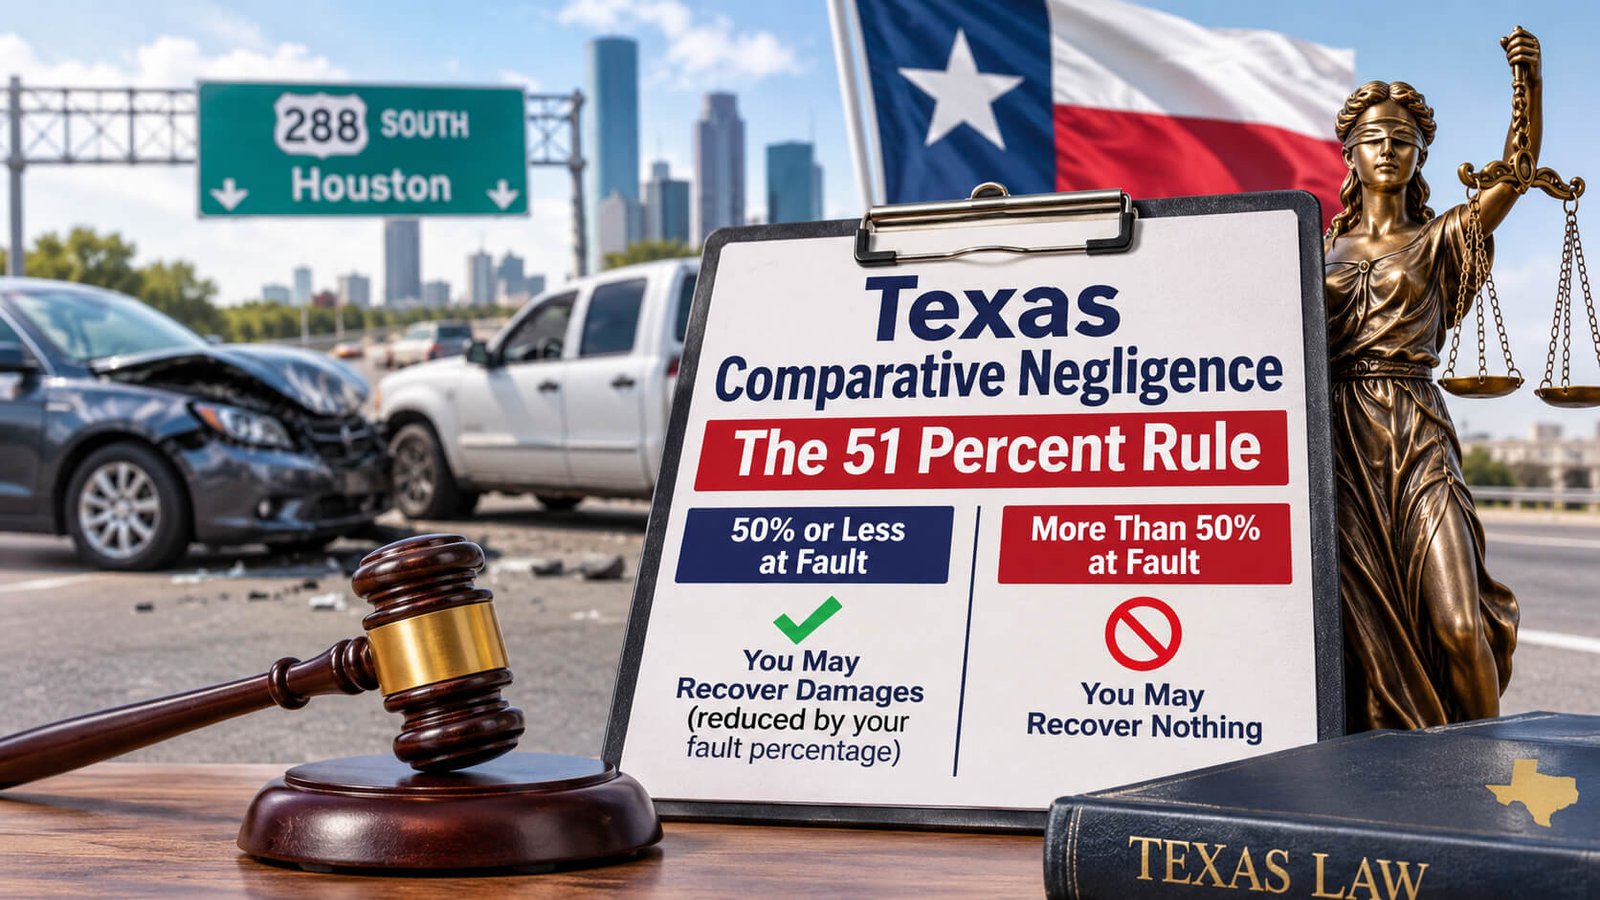
Fault is another factor. Under Texas’s modified comparative negligence rule, an injured person can recover even if partly at fault, provided they are not more than 50% responsible, and the recovery is reduced by their percentage of fault. In my experience, insurers actively use this rule to shift blame onto victims.
Every case at Herrera PLLC is prepared for trial from day one. Most serious injury cases settle without a trial, but an insurer that knows the attorney is prepared to go before a jury is in a different negotiating posture. When a brain injury is fatal, the family may have a claim as well, and our page on wrongful death cases explains how those matters are handled. You can also review our full list of serious injury practice areas.
Frequently Asked Questions
How is a traumatic brain injury claim valued in Texas?
There is no formula that applies to every case. A claim is generally evaluated by looking at medical expenses, future care needs, lost income and earning capacity, and the effect on the person’s quality of life. Texas has specific rules on how some of these are proved, including that medical expenses are limited to amounts actually paid or incurred and that lost earnings are presented net of income tax. A “mild” diagnosis does not by itself limit a claim, but it can affect how an insurer views it. Each case is different, and no result can be guaranteed. An attorney can evaluate the facts of your situation.
What is a life care plan?
A life care plan is a document that projects the future medical and support needs of a person with a long-term injury and the estimated cost of those needs. It is usually developed with input from medical and vocational professionals and is grounded in the medical record.
Can I recover lost future earnings after a brain injury?
Texas law may allow compensation for lost future earning ability, depending on the facts and the evidence. Cognitive injuries can affect a person’s ability to work in ways that are not always obvious, and documentation is important. Under Texas law, evidence of lost earnings and earning capacity must be presented net of income tax.
Why do insurers dispute long-term brain injury costs?
Long-term projections can involve large sums over many years, so they draw the most scrutiny. Insurers may emphasize early recovery, question whether symptoms are related to the accident, or challenge future care estimates. Whether a particular challenge has merit depends on the evidence. Texas does not generally cap non-economic damages such as pain and suffering in an ordinary negligence case, which is part of why the long-term picture matters.
How long do brain injury claims take to resolve?
It varies. These cases often take longer than other injury claims because the long-term picture needs time to develop. Legal deadlines still apply, including a general two-year limitation period for most personal injury claims, so it is worth speaking with an attorney early.
This article is for general educational purposes and is not legal advice or a substitute for advice about a specific situation. Brain injury claims depend on the circumstances of the accident, the nature and severity of the injury, the available medical documentation, and the applicable law. Individuals and families dealing with a brain injury caused by an accident are welcome to call Herrera PLLC at 832-891-3210, email jherrera@jh-lawpllc.com, or reach out through the contact page to schedule a free, confidential consultation.
Jonathan Herrera, J.D.
Jonathan Herrera is the founder of Herrera PLLC in Houston, Texas. He spent more than a decade working as an insurance adjuster, founded JH Claims LLC, and practiced insurance defense at Rymer, Echols, and Nelson-Archer before opening his own firm representing injury victims, policyholders, and businesses.