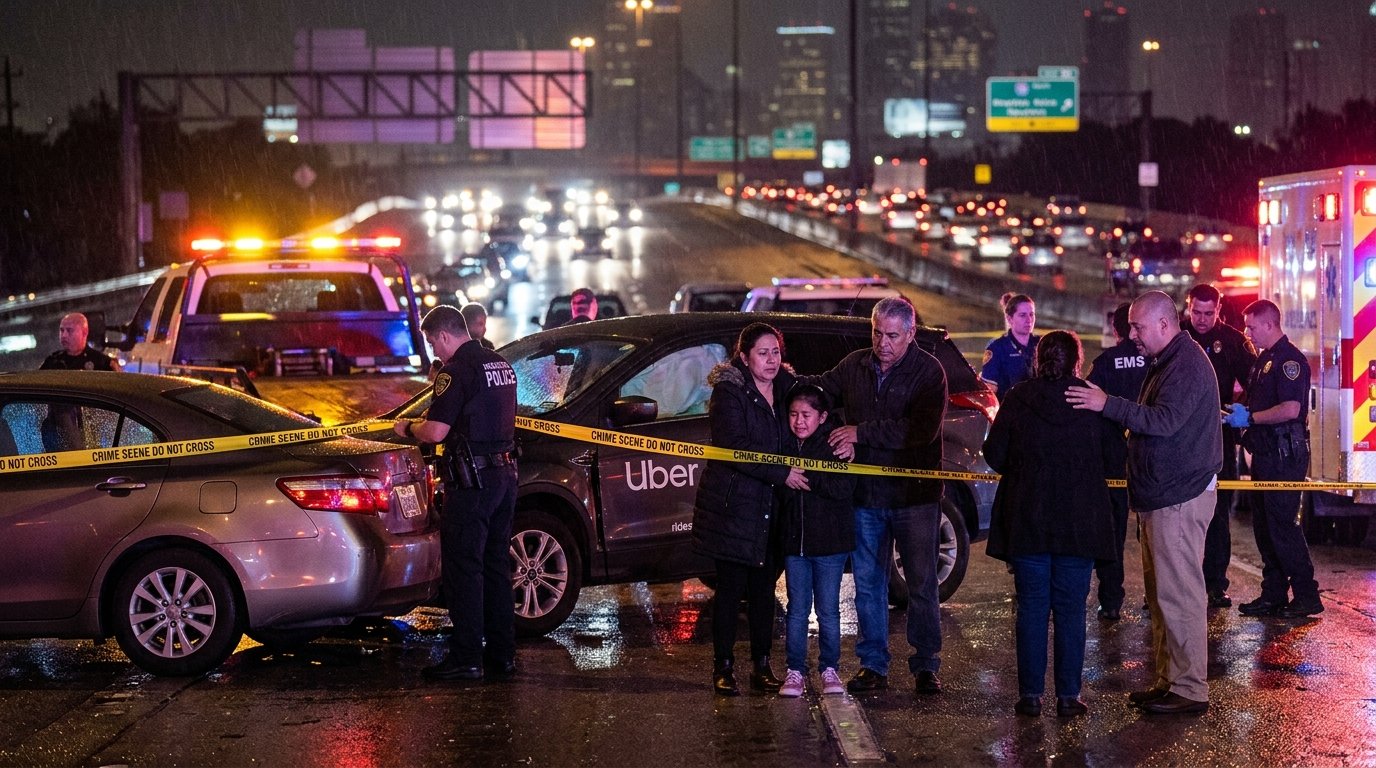

Losing a family member in a car accident is devastating on its own. Discovering that the driver responsible for the crash doesn’t carry enough insurance to cover what your family has lost adds a second layer of injustice on top of the first. In Texas, and across the busy highways and roadways of the Houston area in particular, this scenario is more common than most people expect, and it’s exactly the situation underinsured motorist coverage exists to address.
Herrera PLLC represents families pursuing wrongful death and car accident claims throughout Houston and across Texas, including cases involving underinsured motorist coverage.
Why Minimum Liability Limits Rarely Cover a Fatal Accident
Texas requires drivers to carry liability insurance, but the state’s minimum required limits are modest compared to the real financial impact of a fatal accident. A wrongful death claim can involve lost future income, funeral and burial costs, medical expenses from before death, and the loss of a family member’s care, companionship, and guidance, among other damages. Minimum liability limits are often exhausted quickly against losses of this scale, particularly when the deceased was a primary income earner or a parent to young children. When the at-fault driver’s policy limit falls far short of the family’s actual losses, the gap between what’s owed and what’s available becomes the central problem the family is left facing.
How UIM Coverage Fills the Gap After a Wrongful Death
Underinsured motorist coverage, often called UIM coverage, is a part of a person’s own auto insurance policy designed to step in when the at-fault driver’s liability coverage isn’t enough to cover the full extent of the damages. In a wrongful death context, this means that after the at-fault driver’s liability limits are exhausted, the surviving family may be able to pursue the remaining, unpaid portion of their damages through a UIM claim. This coverage exists specifically because Texas doesn’t require drivers to carry particularly high liability limits, leaving a meaningful number of at-fault drivers underinsured relative to the seriousness of accidents they can cause.
Filing a UIM Claim Against the Deceased’s Own Policy
Under Texas Insurance Code Chapter 1952, UIM coverage generally attaches to the insurance policy of the person seeking to recover, which in a wrongful death case often means the policy carried by the person who died. If the deceased had UIM coverage on their own auto policy at the time of the accident, that coverage may be available to the estate or eligible family members pursuing a wrongful death claim. Determining who has standing to make this claim, and how the proceeds should be handled among surviving family members, depends on the specific facts of the case and the language of the policy involved.
Stacking Multiple Policies in a Fatal Accident Claim
In some situations, a family may have access to more than one applicable UIM policy, whether through multiple vehicles insured under the same household, an umbrella policy, or overlapping coverage in place at the time of the accident. Depending on how the policies are written, it may be possible to combine, or stack, the available UIM limits to reach a higher total recovery than any single policy would provide on its own. Whether stacking is permitted depends heavily on specific policy language and the number of vehicles or policies involved, which makes a careful review of all potentially applicable insurance coverage an important step in a fatal accident UIM claim.
Why Your Own Insurer Can Still Dispute a UIM Wrongful Death Claim
It may seem counterintuitive that a family’s own insurance company would resist paying a UIM claim, but insurers evaluate these claims the same way they evaluate any other claim against their financial interest. A UIM insurer may dispute the extent of the damages claimed, question whether the at-fault driver was truly underinsured relative to the loss, or challenge who is legally entitled to bring the claim.
Having spent over a decade evaluating high-exposure casualty claims from the insurance carrier’s side before becoming an attorney, Jonathan Herrera has firsthand familiarity with how these disputes are built and evaluated internally, which directly informs how UIM claims are handled at Herrera PLLC. Because a UIM insurer is, in effect, standing in the shoes of an underinsured at-fault driver for purposes of the claim, families sometimes find that their own insurer takes an adversarial position despite the ongoing premium relationship. Understanding that this dispute is a normal part of the UIM claims process, rather than a sign that the claim lacks merit, can help families navigate what often becomes a more contested process than the initial liability claim.
Coordinating a UIM Claim With the Underlying Liability Claim
A UIM claim doesn’t exist in isolation. It’s built on top of, and depends on, first resolving or at least establishing the value of the underlying liability claim against the at-fault driver. This typically means pursuing the at-fault driver’s insurance to its full limits first, then turning to the UIM policy for the remaining, unpaid portion of the family’s damages. Coordinating these two claims carefully matters because missteps in the liability claim, including how and when it’s settled, can affect what a family is later able to recover through UIM coverage. Because of this interplay, families facing a potential UIM situation often benefit from evaluating both claims together from the outset rather than handling the liability claim in isolation and addressing UIM coverage only after the fact.
Timing and Cost Considerations
In Texas, wrongful death claims are generally subject to a two-year statute of limitations from the date of death. Because a UIM claim depends on how the underlying liability claim is handled, families are often better served by evaluating both timelines together early on rather than waiting.
Wrongful death and UIM claims at Herrera PLLC are handled on a contingency fee basis, meaning there are no upfront attorney’s fees and no obligation to pay unless compensation is recovered.
If your family is facing this situation after a fatal Texas car accident, Herrera PLLC handles both wrongful death and car accident claims, including cases involving underinsured motorist coverage. Consultations are free, confidential, and come with no obligation. Call 832-891-3210 or contact us online to discuss your family’s specific circumstances.
Frequently Asked Questions
What happens if the at-fault driver did not have enough insurance for a fatal crash?
If the at-fault driver’s liability coverage is exhausted before it covers the full extent of a family’s damages, the family may be able to pursue the remaining amount through underinsured motorist coverage on their own or the deceased’s auto policy, if that coverage was in place at the time of the accident.
Can I file a UIM claim after a wrongful death?
Yes, UIM claims can apply in wrongful death cases when the at-fault driver’s liability coverage isn’t sufficient to cover the family’s losses. Whether a specific family member or the estate has standing to file depends on the facts of the case and the applicable policy terms.
Can UIM coverage be stacked?
In some cases, UIM coverage across multiple vehicles or policies can be combined, depending on the specific language of the policies involved and the number of vehicles insured under the same household. Whether stacking applies requires a careful review of all potentially relevant policies.
Will my own insurer fight a UIM wrongful death claim?
It’s common for a UIM insurer to dispute the value of the claim or other aspects of it, since they’re financially responsible for the underinsured portion of the loss. This is a standard part of the UIM claims process rather than an indication that the claim isn’t valid.
How does a UIM claim work alongside the liability claim?
A UIM claim generally comes after the underlying liability claim against the at-fault driver has been pursued to its full policy limits. The two claims are closely connected, and how the liability claim is handled can affect what’s later available through the UIM policy, which is why many families benefit from evaluating both together from the start.
This article is for general informational purposes only and does not constitute legal advice, and the facts of any specific accident or insurance policy can change how Texas law applies.
Jonathan Herrera, J.D. is a Houston-based attorney and the founder of Herrera PLLC, representing families across Texas in serious injury, insurance law, and civil litigation matters. Before practicing law, he spent over a decade as a licensed insurance adjuster managing high-exposure casualty and property claims for carriers and third-party administrators across multiple states, and he later practiced insurance defense before founding Herrera PLLC. He is a member of the Texas Trial Lawyers Association and the American Association for Justice.